Boot Clutter

Last week my blog was about how clutter seems to hover around me.    I accumulate it daily without effort, it’s an unwanted skill I have acquired over the years.    I am not a hoarder, that would be a compulsive condition I might be able to get medical help for —— Obsessive Accumulating Disorder (OAD), more commonly  known as “Pig Pen’s disease” . Nor am I a collector, there might be some merit in that, who knows I could be on Antiques Roadshow in the years ahead.     But, my stuffs not valuable it is just stuff.

So now we come to my rugby boots.

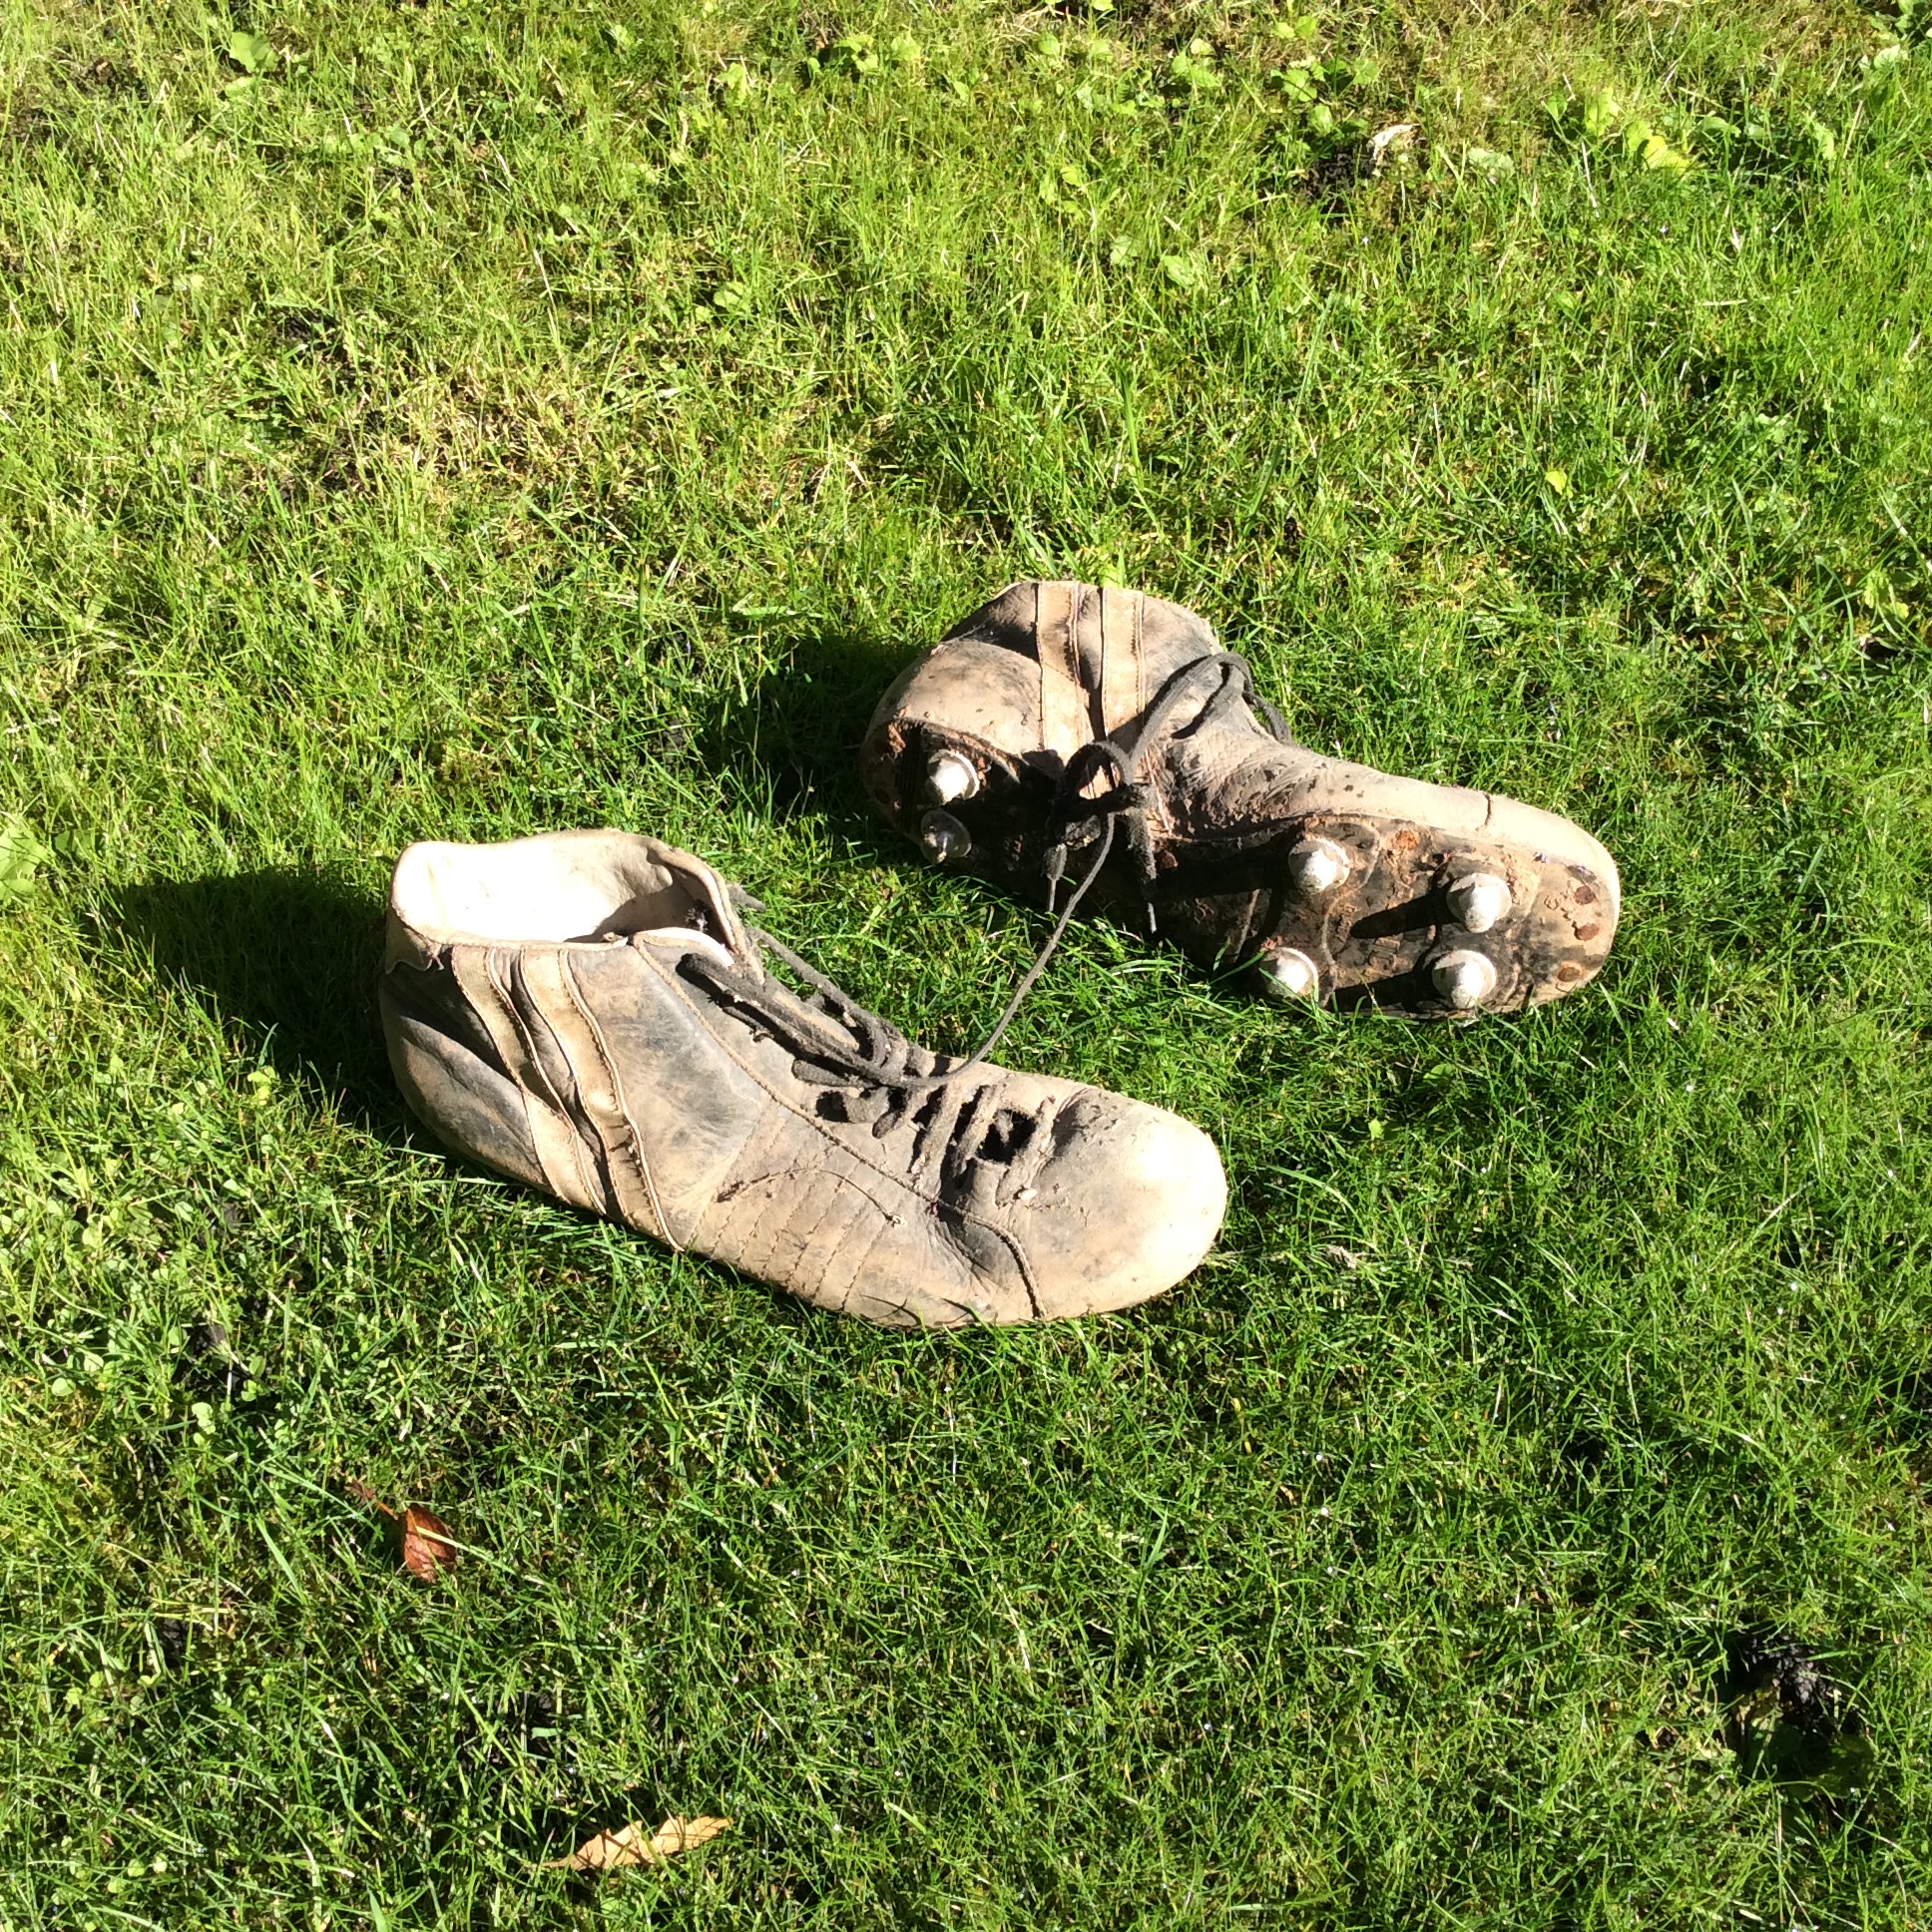
boots

Not too many Rugby players, at 69 years old, still have their boots clean – well, almost clean – and ready to go, but I do.    Just in case, after my glittering career in Syston Thirds, I get a last minute call from Wales to play in the Autumn Internationals, or maybe I could just sit on the bench at the Millennium Stadium.   I am sure I saw a scout on the touchline  30 years ago at Syston and surely he must have seen me?

Therein lies my whole cluttering problem.   Letting go of my memories and wistful unfulfilled dreams is difficult.    I have kept those boots for years, first in my wardrobe and then for the last 20 years in my shed.   Ready to go on a Saturday as soon as the phone rings, or perhaps these days it will be a text message — oops— maybe that’s why I missed it?

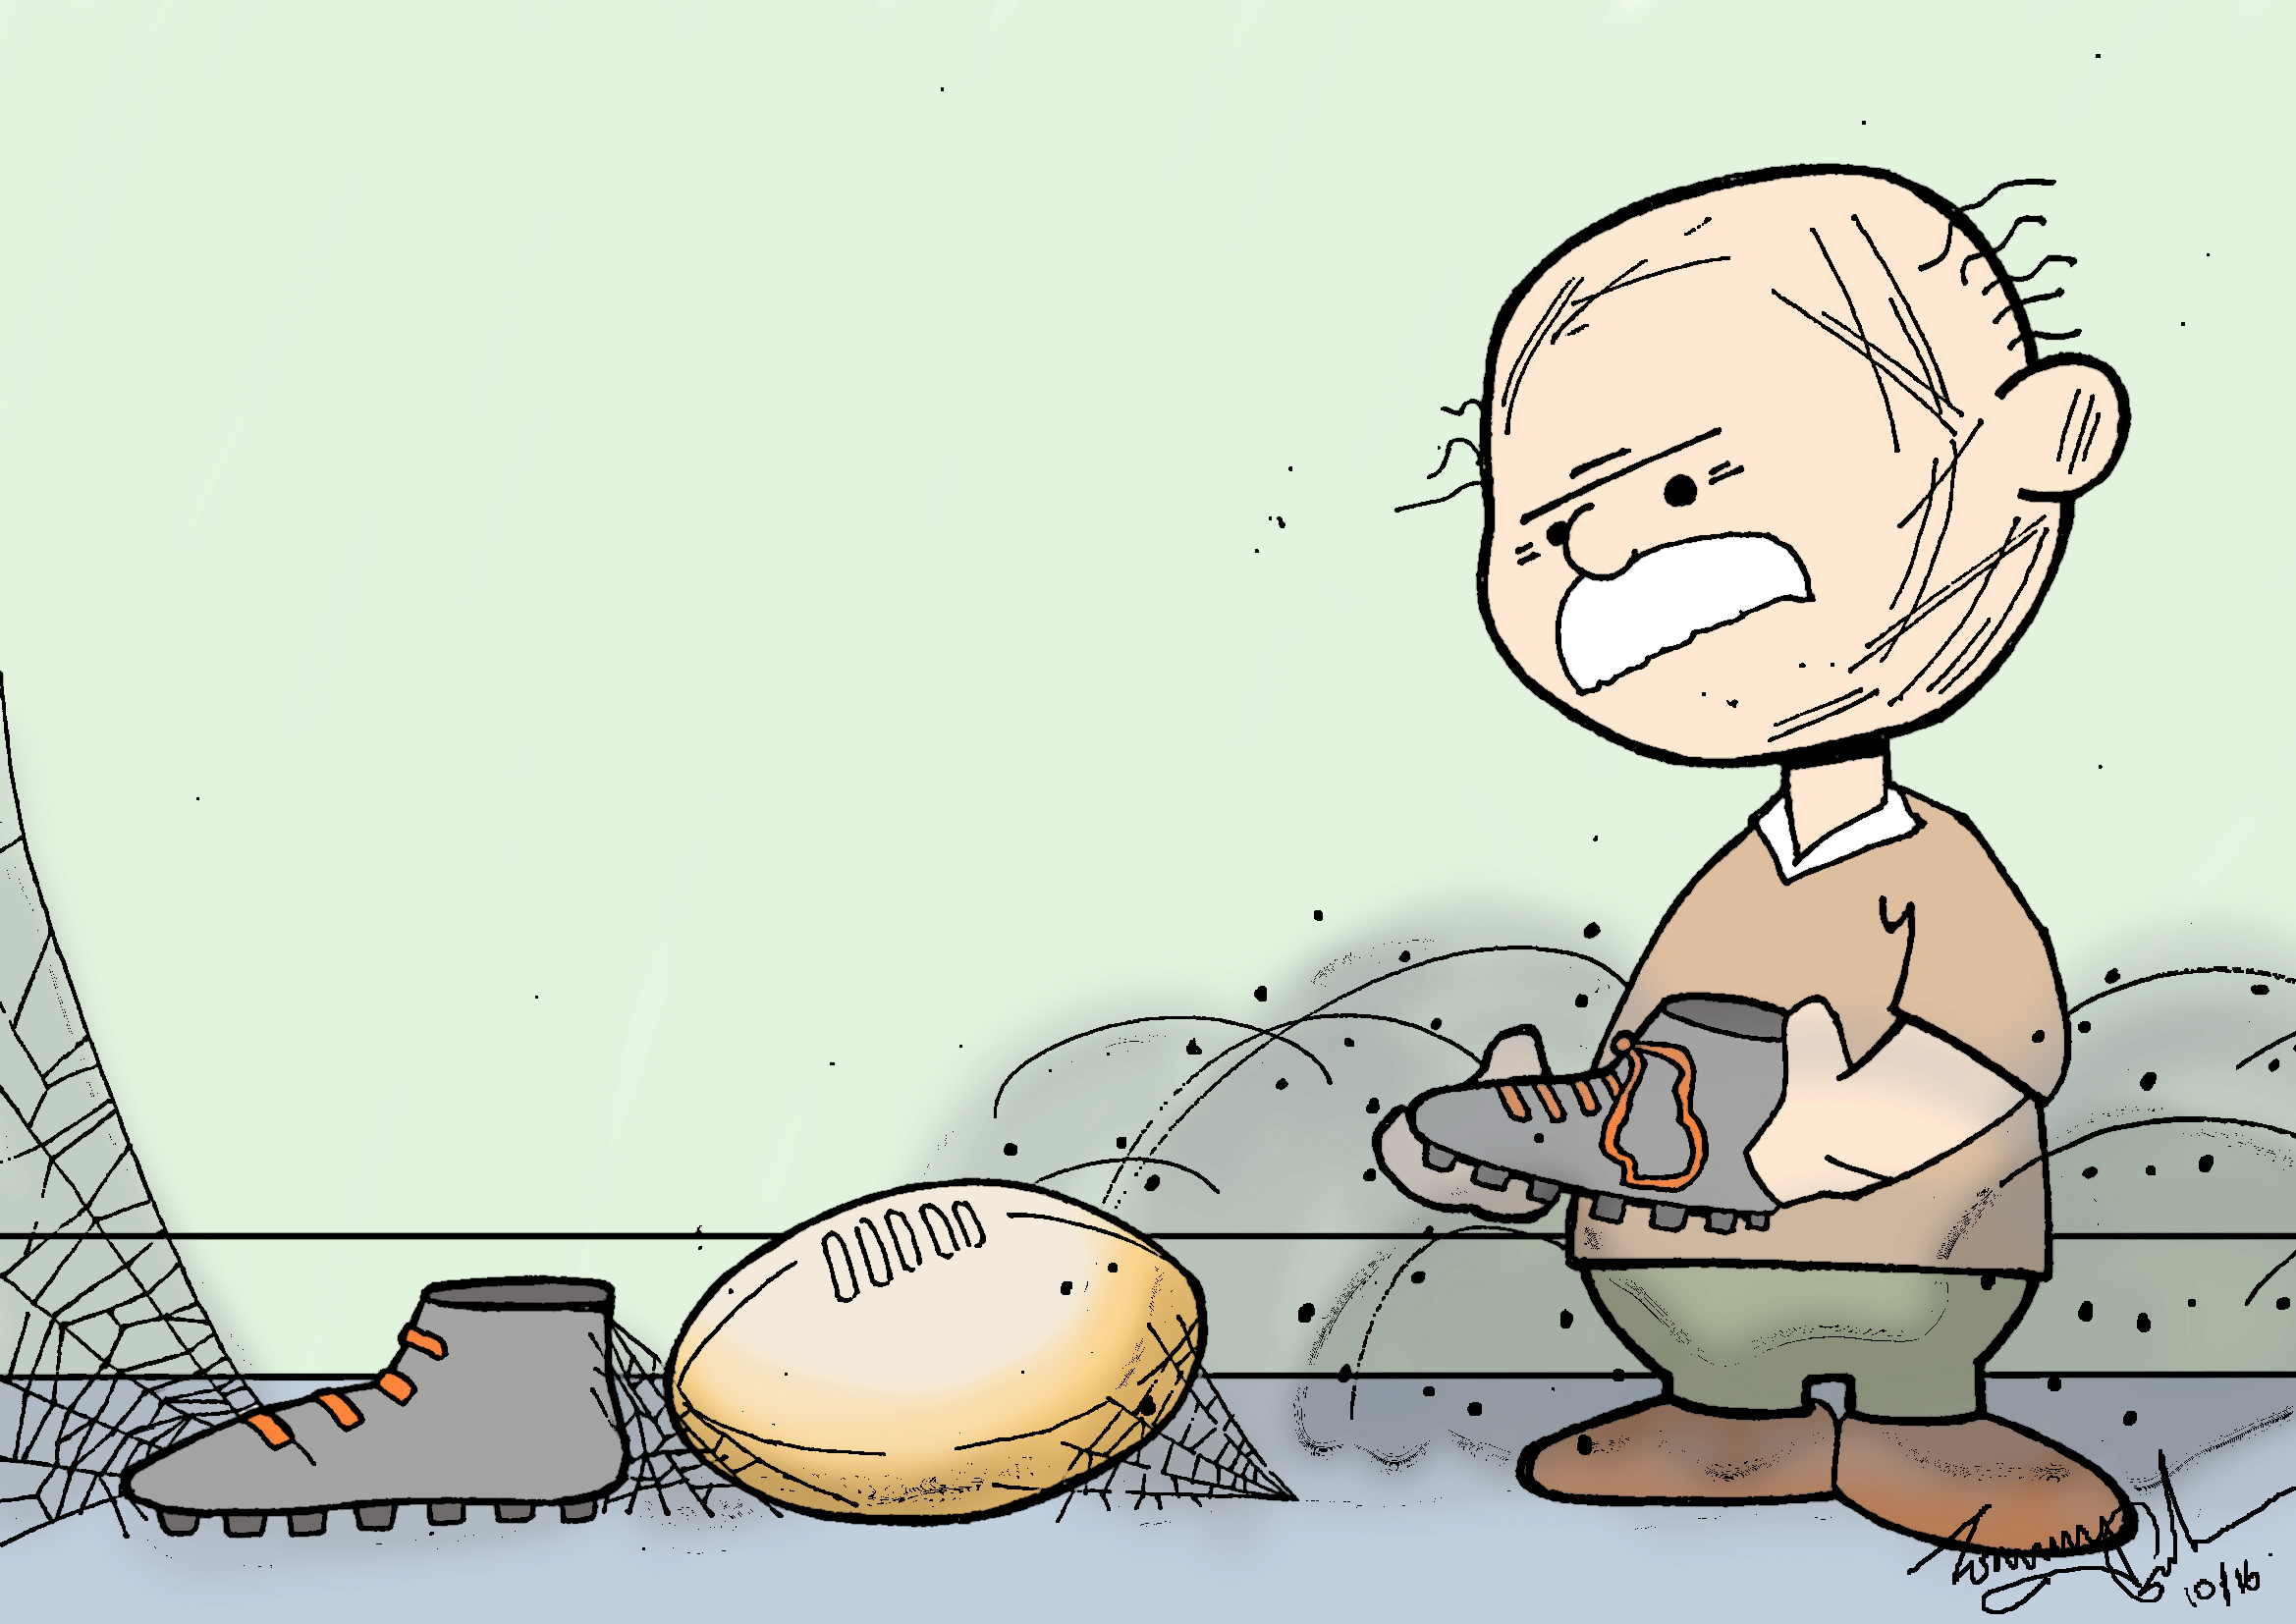
boot-cartoon

Instead of cluttering up my shed, if only I had been more realistic all along I should have thrown those boots away years ago.

It’s obvious I would have to buy new brightly coloured boots if  the call to represent my country finally comes.

Posted in SMILES | Tagged | 4 Comments

Clutter, Clutter, EVERYWHERE !

I haven’t thought about clutter much recently, except every day when I am looking for something, —– which is most days!    I haven’t blogged about clutter for even longer, in fact it was 2013.    (You can see the posts by clicking on ” clutter” in the Tag Cloud )

  • Living a simple life is difficult to do unless you are ruthlessly efficient at throwing things away.  EVERYDAY.
  • It requires complete and constant concentration on the question —————-                  ————— “DO I NEED THIS ?”
  • It applies to everything ABSOLUTELY EVERYTHING.  — The next thing through your door – news papers, letters, flyers, junk-mail,  obviously not people, or at least most people😄  I am not forgetting emails,  but at  least they are up in the clouds until they rain  down one you one day.
  • But also, everything that has come through your door in the past that you did not throw away at the time and now fills up your drawers, your cupboards, any spare shelf space, spare rooms, attics, the garage, all the sheds in your garden and even space in friends garages.
  • You can even hire storage space in a warehouse to keep things you might need in the future.
  • It sounds like the house is untidy — it’s not.    The clutter is hidden away.
  • But it is there, I know it is there and it bugs me  from time to time, when I remember it, or when I can’t find something I know I have put somewhere,but don’t remember where😟

clutter-everywhere

I am going to have an all out attack on my clutter and  clear the clouds of clutter dust that are engulfing me.   It won’t be quick, it won’t be easy, it will take time and determination, there will be setbacks and anguish along the way as  I discard accumulated bits of history.

But I can do it.

I know I can.

Well I think I can.

I will start tomorrow.

Or maybe the day after?


Posted in SMILES | Tagged | 20 Comments

“Timpson Tie Up”

One of the great challenges when you are growing up is learning to tie up shoe laces.  These are the days before Velcro.  Nothing was more embarrassing than not being able to tie your own shoe laces when you went to school.  It was your first big test to show that you were grown up.

Having mastered the tying up skill once, it’s strange how the same great challenge comes back to you again in later life.

Last summer my wife bought me a trendy pair of new shoes from that well-known High Street name in footwear from my childhood – Timpsons.  That’s where the challenge starts all over again!

The shoes were blue leather with white rubber soles and white leather shoe laces.  I was about to be the most fashionable man about town.  I put the new shoes on with childlike enthusiasm, tugged on the laces and one of the laces broke.  The square-shaped white leather laces were so unusual that I couldn’t find any more.  So the shoes went back in the box and were forgotten until this summer.

timson

Then my wife bought me the same new white Timpsons shoe laces.  The great challenge this time was to get the laces out of the packet.  They were tantalisingly encased behind a thick plastic cover sealed to an equally thick cardboard backing.  Nobody intended you to get these laces out easily.  There were no perforations in the cardboard, no fold away tear-off corner and the plastic was impenetrable.  This must be Timpsons’ last laugh.

When I eventually got the packet open with a crow bar……the laces were far too long.  I would have known this if I had read the instructions on the back, but I didn’t have my magnifying glass with me at the time.  Now with that in hand I can clearly see that I need a degree in shoeology to buy the right shoe laces, then I would know that with only two pairs of eyelets I only need 45 centimetre laces.  Sadly, I bought 100 centimetre laces which is long enough for 9 pairs of eyelets.  So now I need more eyelets!

Two other things I noticed in the small print on the back of the packet.  Firstly, all Timpsons laces are guaranteed for 6 months.  Secondly, they hope I enjoy wearing my new Timpsons Laces.

The final irony is the Timpson motto:

Great service for great people!

Posted in Grey Products, SMILES | 2 Comments

Retirement Housing – A Game Changer.

This post follows on from my previous post and builds on the many comments I have had on this and earlier posts on the subject of Retirement Housing.   (You can find them all in the Topics List under the “Retirement Housing” heading)

A radically different approach is needed, which will require the post-war baby boomer generation of children to accept that their parents aspiration of free health care and decent housing for everyone is only possible if they use the wealth they have fortuitously accumulated in their houses as property prices have risen.    The legacy they had hoped to pass onto their children and grand-children must first be called on to pay for their own health.    The added years of increased longevity  requires much more money than most have saved in their pensions.

The two big uncertainties older people face are about their health and their wealth.    Will they need more support/ health care as they grow older and put bluntly –  will their money run out  before they die?    The problem is that nobody knows.

“Head in the sand” is the most common individual reaction.   Most people hope to die a sudden death, but the evidence is that only 10% do.   The majority have a period of chronic illness before they die.   Long term  health care could be the answer, but it is expensive and people are reluctant to pay for an uncertain risk.

“Head in the sand” is also the Governments’ response, as all politicians are reluctant to honestly tell older people they are going to have to pay for their own care in later life.   Meanwhile, pressure continues to build up on the NHS and Social Services and the quality of care reduces.  Around this a blame culture developes and nobody looks for strategic solutions.

The answer is buried in the equity most older people (80%) have tied up in their houses.   The problem is that it is difficult and expensive to unlock.

Equity release has justifiably earned itself a bad name.  It is expensive because of the unpredictability of lifespans and the fluctuations of housing values.   So there needs to be a new, cheaper and more flexible answer to releasing equity in your home.

Retirement housing is in short supply and is holding its value, reinforced by a market where many purchasers are downsizing from larger more valuable houses and consequently are not so price sensitive  when buying a smaller home.   The market is primarily driven by quality of accommodation and lifestyle.    There is no point in moving unless your new home offers a better life.   Down-sizing on its own is only part of the answer — it solves wealth but not health.

Some people will have  money left  after down-sizing but for others they may need to continue to release more equity  to pay for health care and support.   Many people will have lived in lower value homes which only allow for part purchase of a new retirement home.   In both cases flexible shared ownership housing and the ability to continue to sell back further shares over time is an answer.

Traditionally shared ownership allows young people to  get a step on the housing ladder and then buy additional shares until they own their new home outright.     We need to completely reverse that thinking for retirement housing and allow older people to gradually release their equity share if they need resources to pay for care.

Retirement housing provided by charitable Housing Associations, which has a significant element of shared-ownership can appeal to a lot of asset rich and income poor older people.    Add to this the option of stair-casing down to release funds for health care  and you have facilitated the answers to future health and wealth.

This is not new thinking just a new mindset.   The caveat is that it must be simple and easy to do – no conveyance lawyers, just an open and transparent exchange of letters providing a release of capital  in exchange for shares given back to the Housing Association, underwritten by a charge on the property.

Governments won’t do it, because they do not think holistically about housing and health, nor are they prepared to face up to the truth about who pays for the cost of health care for older people.    Only forward thinking Housing Associations prepared to break the moulds of past housing models can create new opportunities for older people to look after themselves in later life.

In the latter half of the last century Housing Associations changed the lives of many older people with their provision of sheltered housing.   The question is will they again have the courage and passion to be :-

mansmilew-bigboard-cropped-183

Posted in RETIREMENT HOUSING | 4 Comments

Retirement Housing – Government Perspective.

This follows on from the previous blog on my market overview of retirement housing.

The current Government only has housing for new starters on the housing ladder in it’s sights.    They see retirement housing as a luxury only to be made available to those who can afford to buy.  What’s more this may well become a self-fulfilling prophesy if left to the private sector housing developers.

From a narrow and historical perspective the Government may be right.   In the past publicly funded social housing for older people required  huge capital grants, which remain tied up in those houses to this day.   In addition, the majority of the tenants are dependant on housing benefit to pay some or all of the rent and service charges.

The days of large capital grants have long disappeared, along with any significant supply of new social housing.   More recently the treasury has turned it’s cost cutting eye to reducing the level of housing benefit.    These two austerity measures have  all but eliminated the financial viability of new retirement housing schemes for social rent.

This one-eyed view ignores the social and health benefits of retirement housing.   Furthermore, there are proven savings to health and social care.

You have to have an holistic approach and wide horizons to find a way ahead for social housing for older people.   It needs to make real and transparent the savings to the NHS  and to Social Services, as well as selling itself to older people themselves as a positive improvement in lifestyle.

Lets hope the Housing  Association movement can rise to this new challenge.

Posted in RETIREMENT HOUSING | 2 Comments

Retirement Housing – A Market Overview

I have written a lot about the current state of the retirement housing market in the last twelve months,though it mainly reflects the relative inactivity in a stalled housing economy.    ( You can see my earlier posts by clicking on “Retirement Housing” in the topics list)

At a time when more and more of the baby boomer generation are entering retirement age and looking for new options in later life, there is a massive mismatch between demand and supply.   Or, perhaps more accurately between aspirations and opportunities.  There are simply not enough houses on the supply side, however, the demand is skewed by a host of factors related to both affordability and suitability.

There are expected to be an extra 3.5 million older households in England by 2033.   A 60% increase, which will mean that a third of all households will be occupied by people aged over 65.

Currently only 2% of older people live in specialist age related housing.  This has the potential to rise to 5% in the next decade, but only if the supply of new retirement housing increases dramatically.

It is a great opportunity, if we take it, or leads to a big problem, if we don’t.

I will expand on this theme in the days ahead.

Posted in RETIREMENT HOUSING | 1 Comment

“Daylight Robbery”

Most robbery is done in the dark.  More daring robbery in the day usually requires a disguise.

Pirates had patches over one eye.  Stagecoach robbers in cowboy films had their neckerchiefs pulled up over their faces.  Modern day jewellery thieves and bank robbers usually go to the trouble of donning a balaclava for their heists.

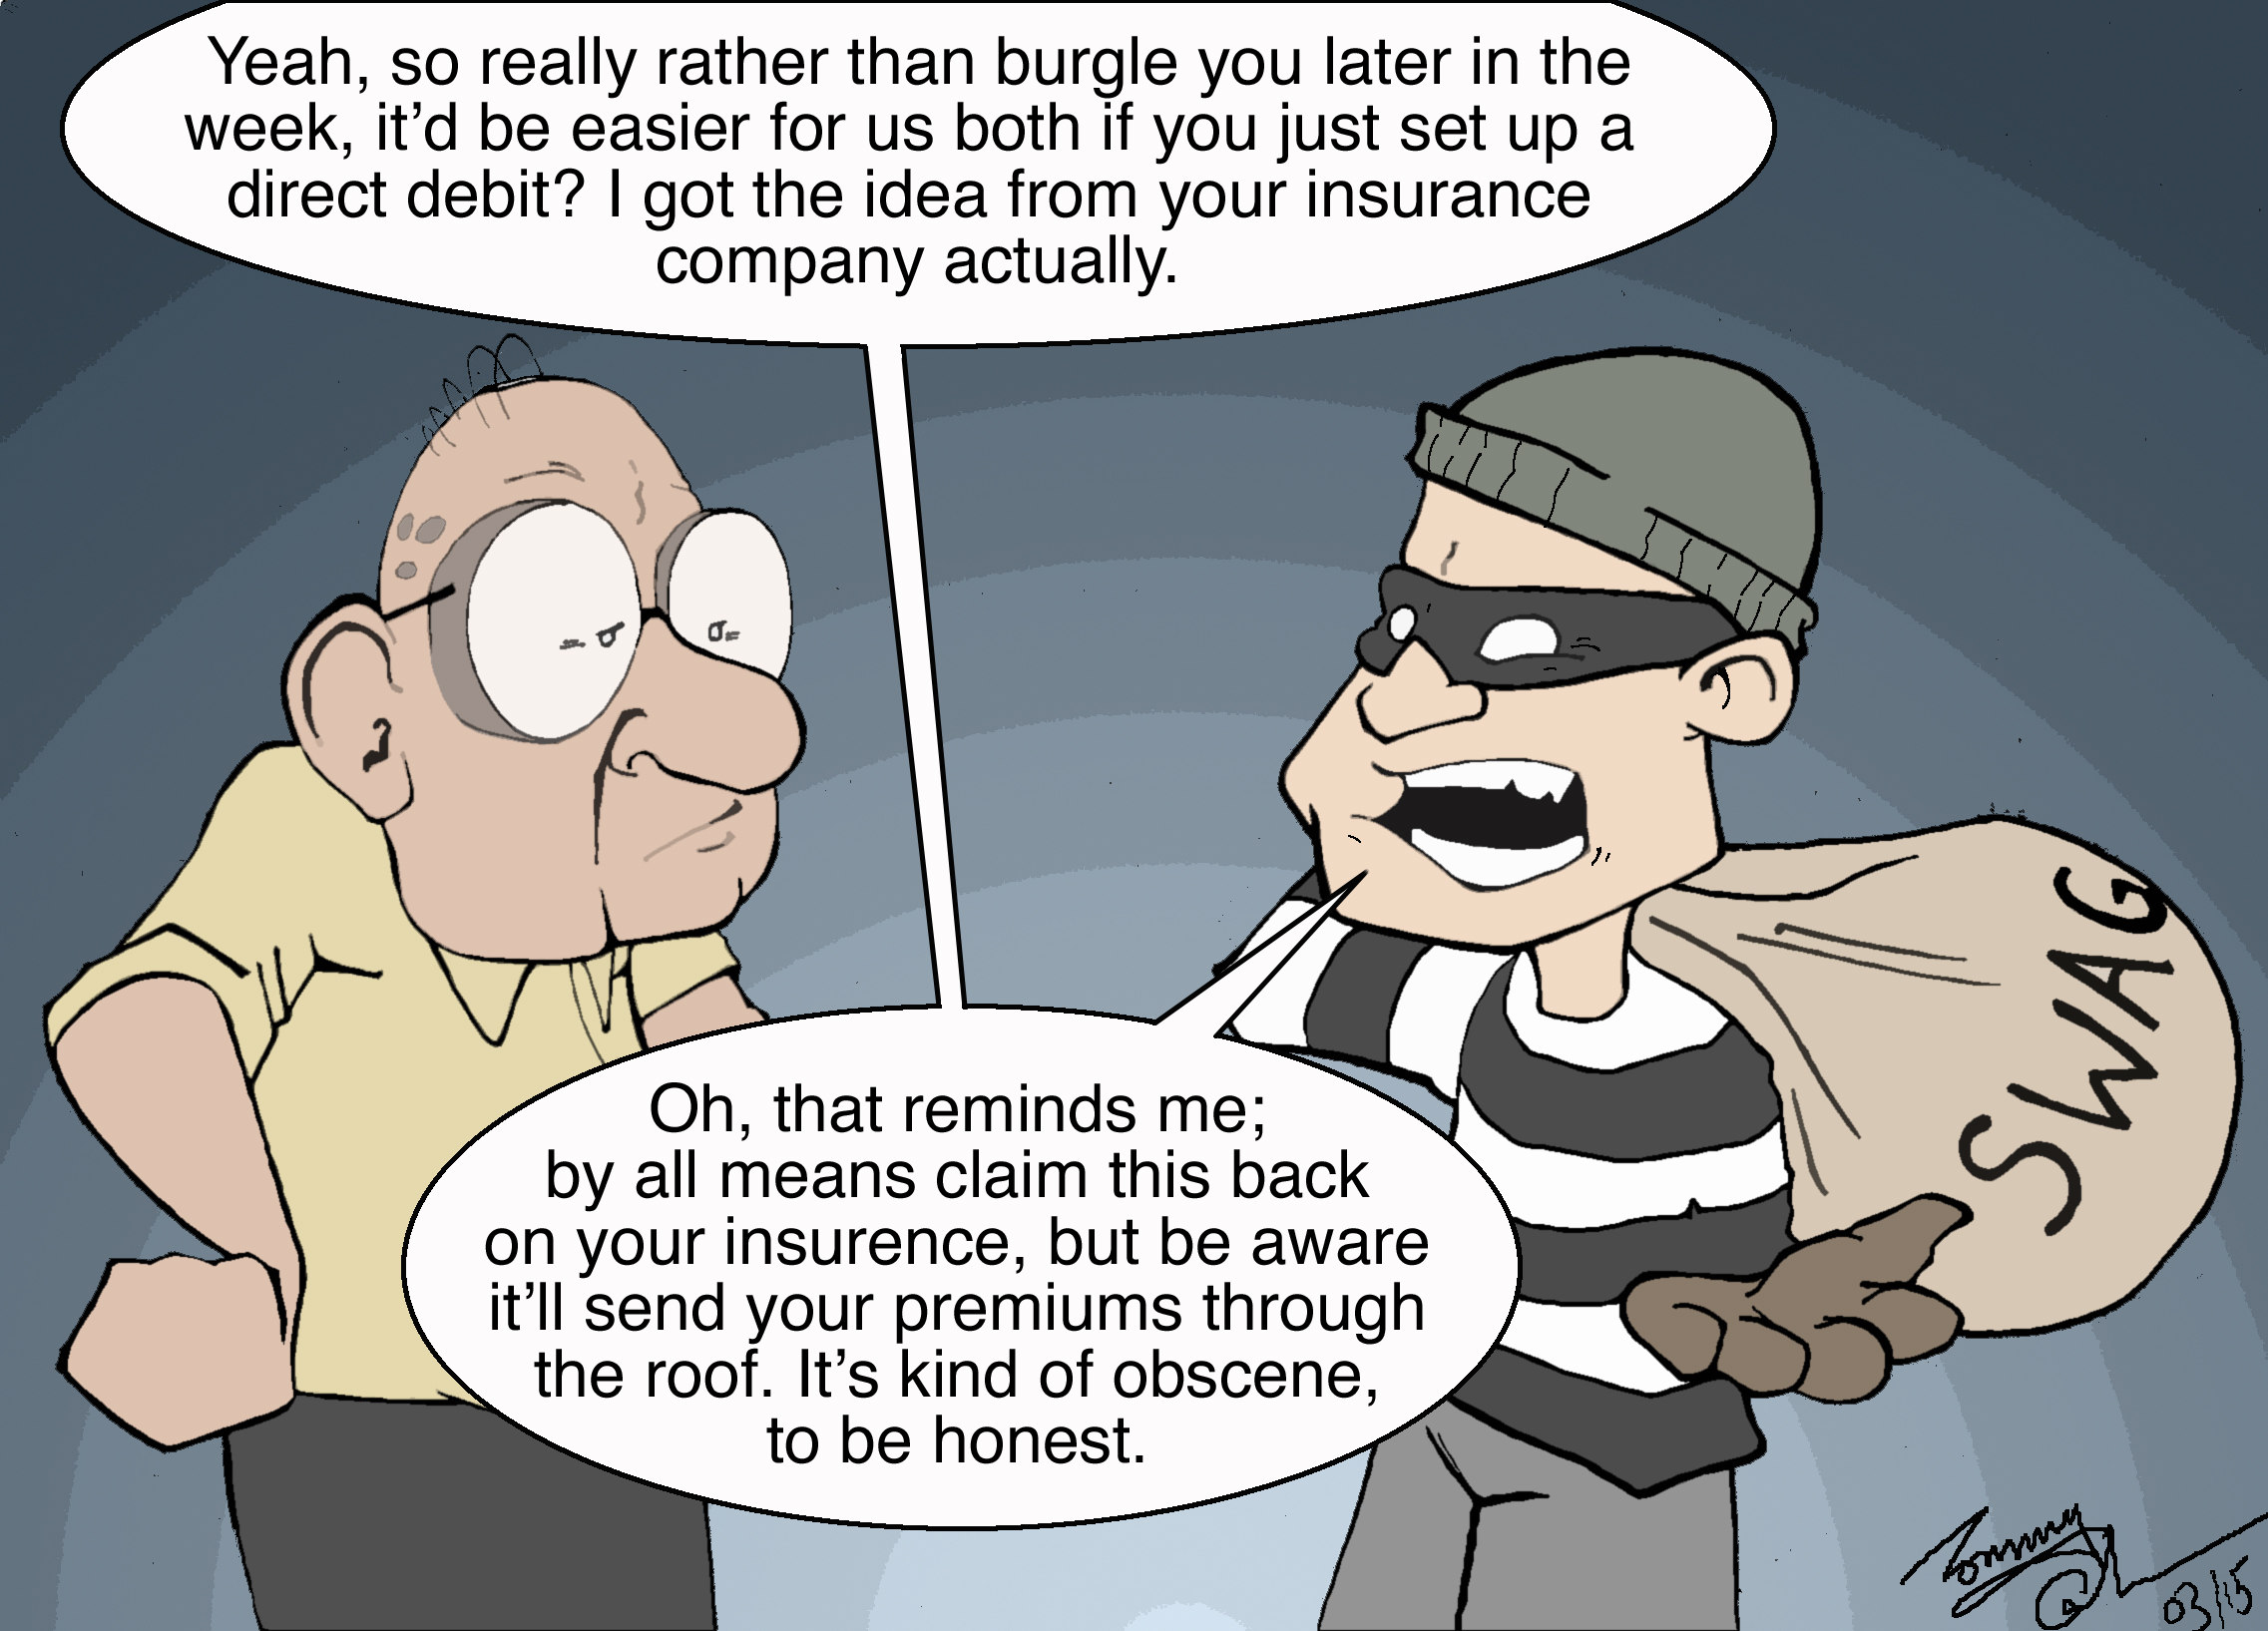
Today’s insurance salesmen are much more brazen, particularly with older people.  They come well dressed in grey suits; they don’t bother with a disguise, they hide behind their “trusted” brand.

A recent report in Times Money covered the cases of a number of elderly people who found they were paying way over the top for insurance renewals.

An 89 year old was paying five times as much as new customers for building insurance.  When they were finally exposed after the man had died, Lloyds merely pointed out that the man “could have cancelled his insurance at any time”.   Not so much a trusted friend as buyer beware !

In another example, a daughter found her mother was paying more than twice the going rate for house insurance.   After they were rumbled, Aviva claimed it was a “miscalculation”.

It appears there are many more examples like this where insurance companies exploit the fact that at renewal time, elderly people are less likely to shop around and switch providers.    Most older people are used to being able to trust their insurance company to treat them well.     It now seems that trust maybe misplaced.

Who knows what they will be upto next ?

daylight robbery copy

Posted in Grey Products | 4 Comments

“NHS Crisis Looming”

Over the summer months, the NHS has regularly been in the news headlines again with one problem after another.  Here are two recent examples:- “Thousands have surgery cancelled at last minute” (The Times – 15th August) “Dementia care lottery exposed” (Daily Mail – 16th August) There are many more stories in the media about hospitals under pressure; extended waiting times at A & E; reduction of health services and threatened closure of departments due to cuts in budgets. BUT, the headline that caught my eye most was in The Times on the 12th August:-

“NHS crisis deepens as bed blocking costs £6 billion”

You would think this would herald a great debate.  After all £6 billion is a lot of money.  To quote from the article again, the situation was:- “pushing hospitals to breaking point” “tens of thousands of patients experienced delay in being discharged” “A & E waiting times for June were the worst ever” “the shortage of emergency doctors was leading to a real crisis” “ambulance response times failed to meet the required standard” “cancer care waiting times also missed their targets” Fortunately a week later, The Times printed this retraction, albeit in a very small front page paragraph which would be easily overlooked:- “We said in a front page report that bed blocking costs the NHS £6 billion a year.  Official estimates put the costs at £820 million.  We apologise for the serious error”.

So that’s alright then!

The fact that nobody was alarmed, either by the headline or the crisis situation that was described in the article beneath, should tell us a lot about the way the NHS is perceived today.  Everyone knows that the total cost of the NHS is astronomical and a few billion pounds being lost in one way or another is accepted as small change.  Equally nobody seems to be alarmed about the dramatic descriptions about the crisis in the NHS since we all seem to feel that little can be done about it. The very fact that other parts of the media didn’t instantly correct the Times’ miscalculation, says much about the way that they too have given up on controlling the black hole that NHS finances had become. It all reinforces the myth that older people are causing the problem in the NHS because not only do they get ill, but when they are eventually hospitalised, they stay in for far too long.  Perhaps “society” thinks that older people enjoy their stays in hospital so much that they would like to extend their holiday away from home.

hospital2

None of this makes sense but neither do alarmist headlines in The Times.

Posted in N.H.S. | 2 Comments

It’s your funeral 😄

Buying a funeral plan is a way of making sure there is  enough money to pay for your last big send off yourself, rather than leaving the bill to be picked up by unhappy relatives when you are gone.   Especially if you want to go out in style, you know — wheeled carriages, four black horses, stretch limos full of hundreds of weeping Facebook flash mob friends, loud speakers outside the church for the overflow audience of clapping fans  who never knew you …….. and flowers lots of flowers.    A modest respectful sort of funeral😢

Last year 183,500 funeral plans were taken out, which is a 25% increase on the year before.  Sounds like death is a growing business. On average a plan costs £3,550.   Not sure that includes a round of drinks at the wake ?

Funeral costs are rising rapidly and are forecast to double in the next 10 years.     So buy you plan while you can!

It pays to shop around, so why not start at your local supermarket —- ASDA has a funeral plan although at the check out they prefer to call it ‘life insurance’.    Speak to the check out lady when you next get your weekly  groceries.

If you don’t shop at ASDA then try the Co-op, they are the UK’s brand leader when it comes to funeral send offs.     They have 1200 outlets (sorry, funeral parlours) in the UK and if you purchase on-line you get a £100 discount on you funeral plan.   They have bronze, silver and gold plans, which is certain to create an argument amongst  your relatives 😄.       I wonder if you can also use your Co-op green stamps  for the final payment ?

Another option, particularly if you want to ascend in a puff of smoke into the clouds (although Heaven is not a guaranteed destination for everyone) is to use Dignity,  the UK’s  largest owner of crematoria.   Not to be confused with Dignitas which includes a final trip to Switzerland.    Dignity operate on a gargantuan scale — 39 crematoriums throughout the UK, 750 funeral directors and a further 400 ‘vetted’ directors, so your pets can come too.   In their advertising, they pride themselves on the fact that “98% of their customers would recommend them to friends and relatives”.    That must be clear evidence that there is life after death.

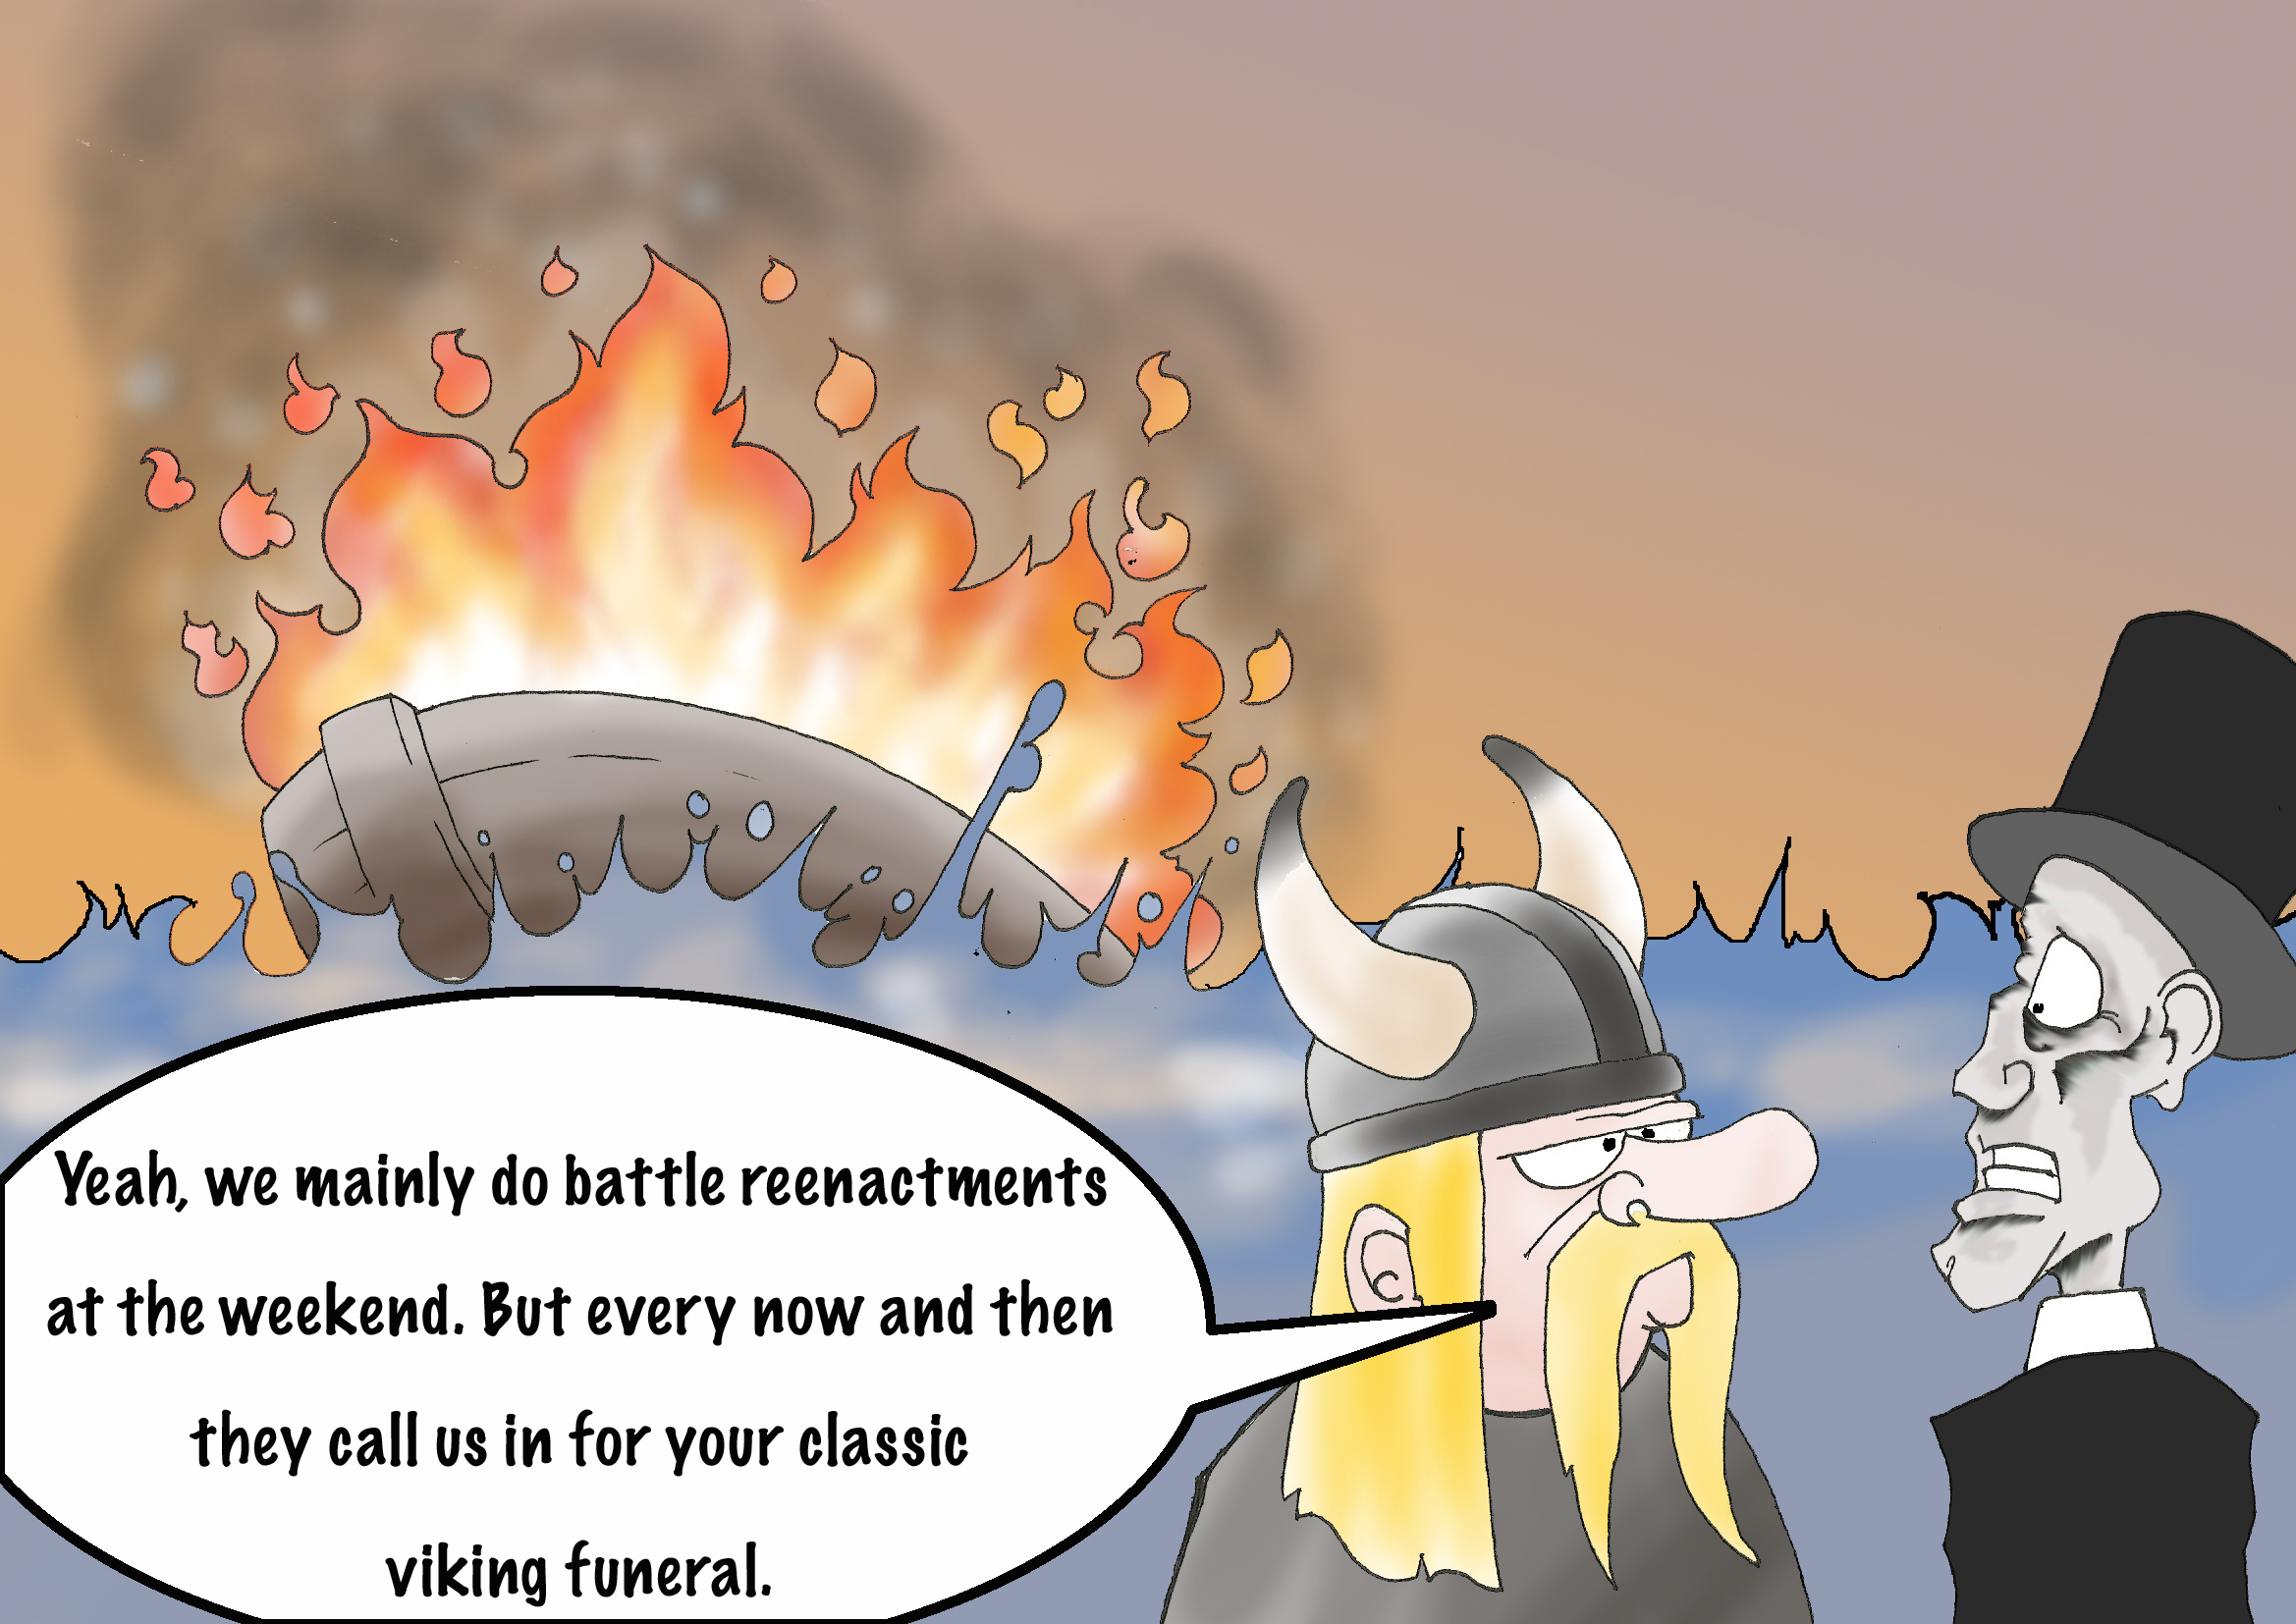
One last thing on this sombre subject.    Apparently we are running out of land for burials. So it rather looks like I will have to have that ostentatious Viking burning-boat-burial at sea after all.

viking

Better take out the “luxury tailored funeral plan”. 😄

Posted in Grey Products | 6 Comments

“Bungalow conflation”

I have never had a conflation before, but it is a trendy word to use, which is in the news a lot recently, so hear goes.   My last two blogs have been about the planners restrictions on building houses and the desire of many older people to retire to a bungalow.    Let’s try and conflate these two ideas.   The planners want higher density housing to limit the need for building on green field sites, which directly conflicts with the demand from older people for more bungalows.    Indeed the last thing the planners would want is lots of bungalows dotted all over the place😟     How about we turn the bungalow aspirations into large specially designed retirement flats, with level access throughout and lifts to all other floors.    Then add a range of facilities on your doorstep, including a shop, a coffee bar and some activity spaces.   That way you will have plenty to do, rather than being isolated in the country.   Let’s call it a retirement village !   Better still locate it in the town where you already live.    That way you will still be close to your family and friends and the planners will be able to keep their green belt.    So everyone will be happy 😄😄😄😄😄😄😄😄😄😄 and heave a lot more fun in retirement !

ferris2

Conflation is not a bad idea !

Posted in RETIREMENT HOUSING | 5 Comments